

Multi-Trex delayed financial statements 2026 research needs three separate status checks: audit work, governance approval and public filing. In its 2 November notice, the company said the audit had concluded, while governance meetings remained scheduled. It expected to file the audited accounts by 20 November, following approval. A stated target is not evidence that filing has occurred.
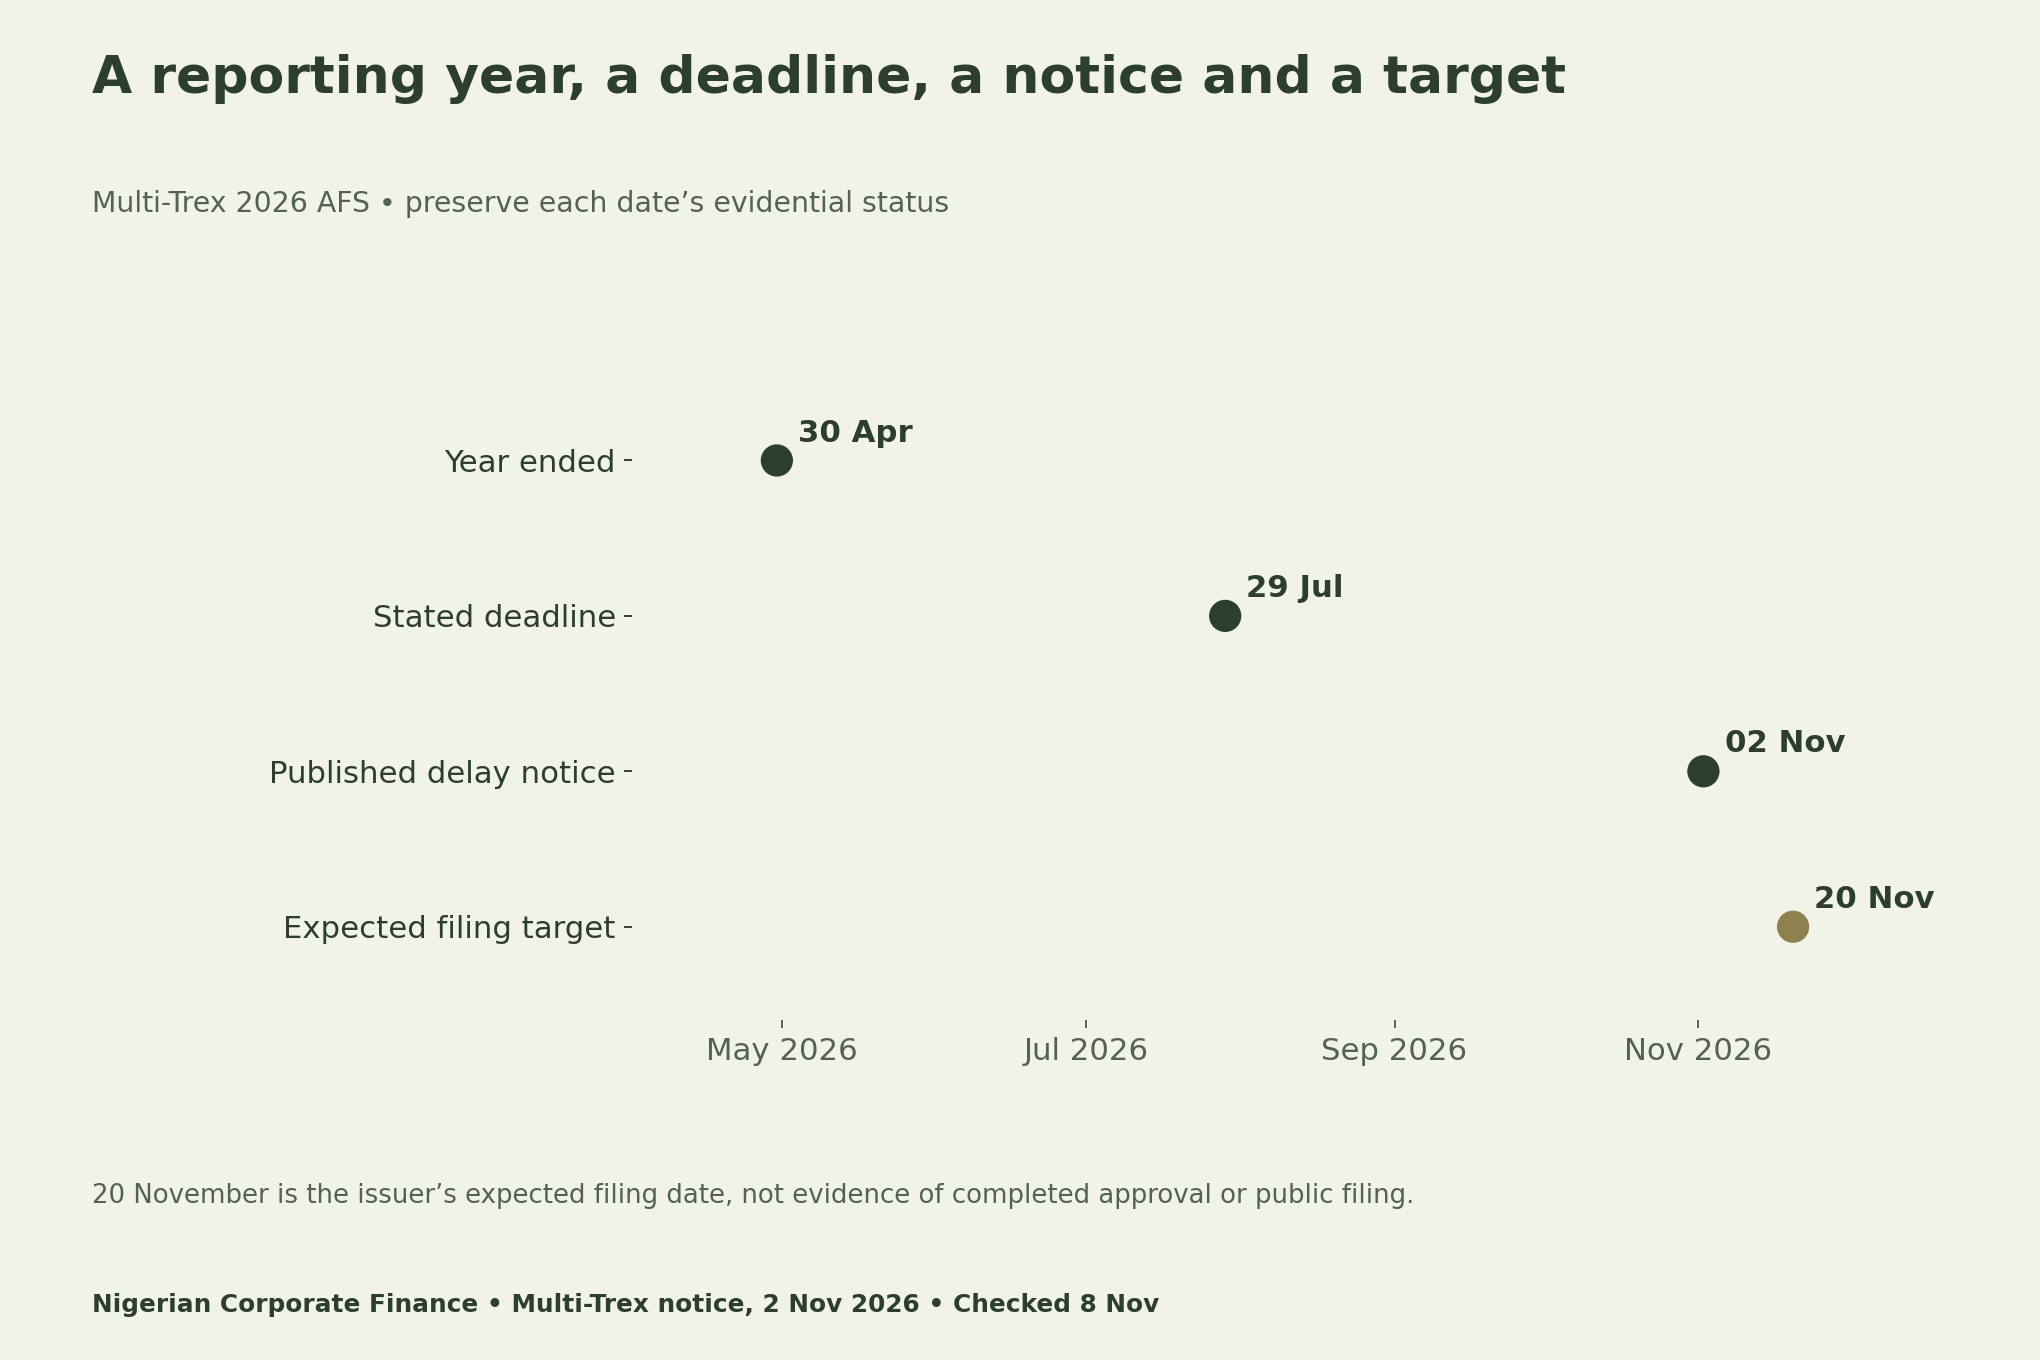
The notice concerns the year ended 30 April 2026 and gives 29 July as the filing deadline. Ordinary date subtraction places the notice 96 calendar days after that stated deadline. The 20 November target lies 114 days after it, and 18 days after the notice. These intervals describe the chronology; they do not calculate fines or interpret a moratorium.
Research checked on 8 November 2026. The reviewed official issuer page lists the delay notice and separate unaudited 2026 reporting documents. We did not identify the completed 2026 audited accounts in those reviewed links. This is a dated reporting-process analysis, not a claim about the missing accounts’ results or auditor opinion.
Multi-Trex delayed financial statements 2026: read the dates
The official delay notice hosted by NGX distinguishes the reporting year, the stated deadline, the announcement and the expected filing date. Keep those fields separate in a register. An unaudited year-end document does not become the missing audited financial statements simply because it covers the same year.
| Event | Date | Evidence status |
|---|---|---|
| Reporting year end | 30 April 2026 | Historical reporting boundary |
| Stated filing deadline | 29 July 2026 | Historical stated deadline |
| Delay notice | 02 November 2026 | Published issuer notice |
| Expected filing by | 20 November 2026 | Prospective issuer target |
The notice says the cure period had also expired. We attribute that statement to the company. This article does not reconstruct the applicable cure-period rules, assess sanction exposure or determine how a moratorium affects obligations. Those questions need current official terms and appropriately qualified review.
Calculate the elapsed days with a stated convention
Our convention is end date minus start date using ordinary calendar dates. We do not add one for both endpoints, adjust for weekends or calculate business days. Therefore, 2 November minus 29 July equals 96 days. The 20 November target minus 29 July equals 114 days. The target minus the notice date equals 18 days.
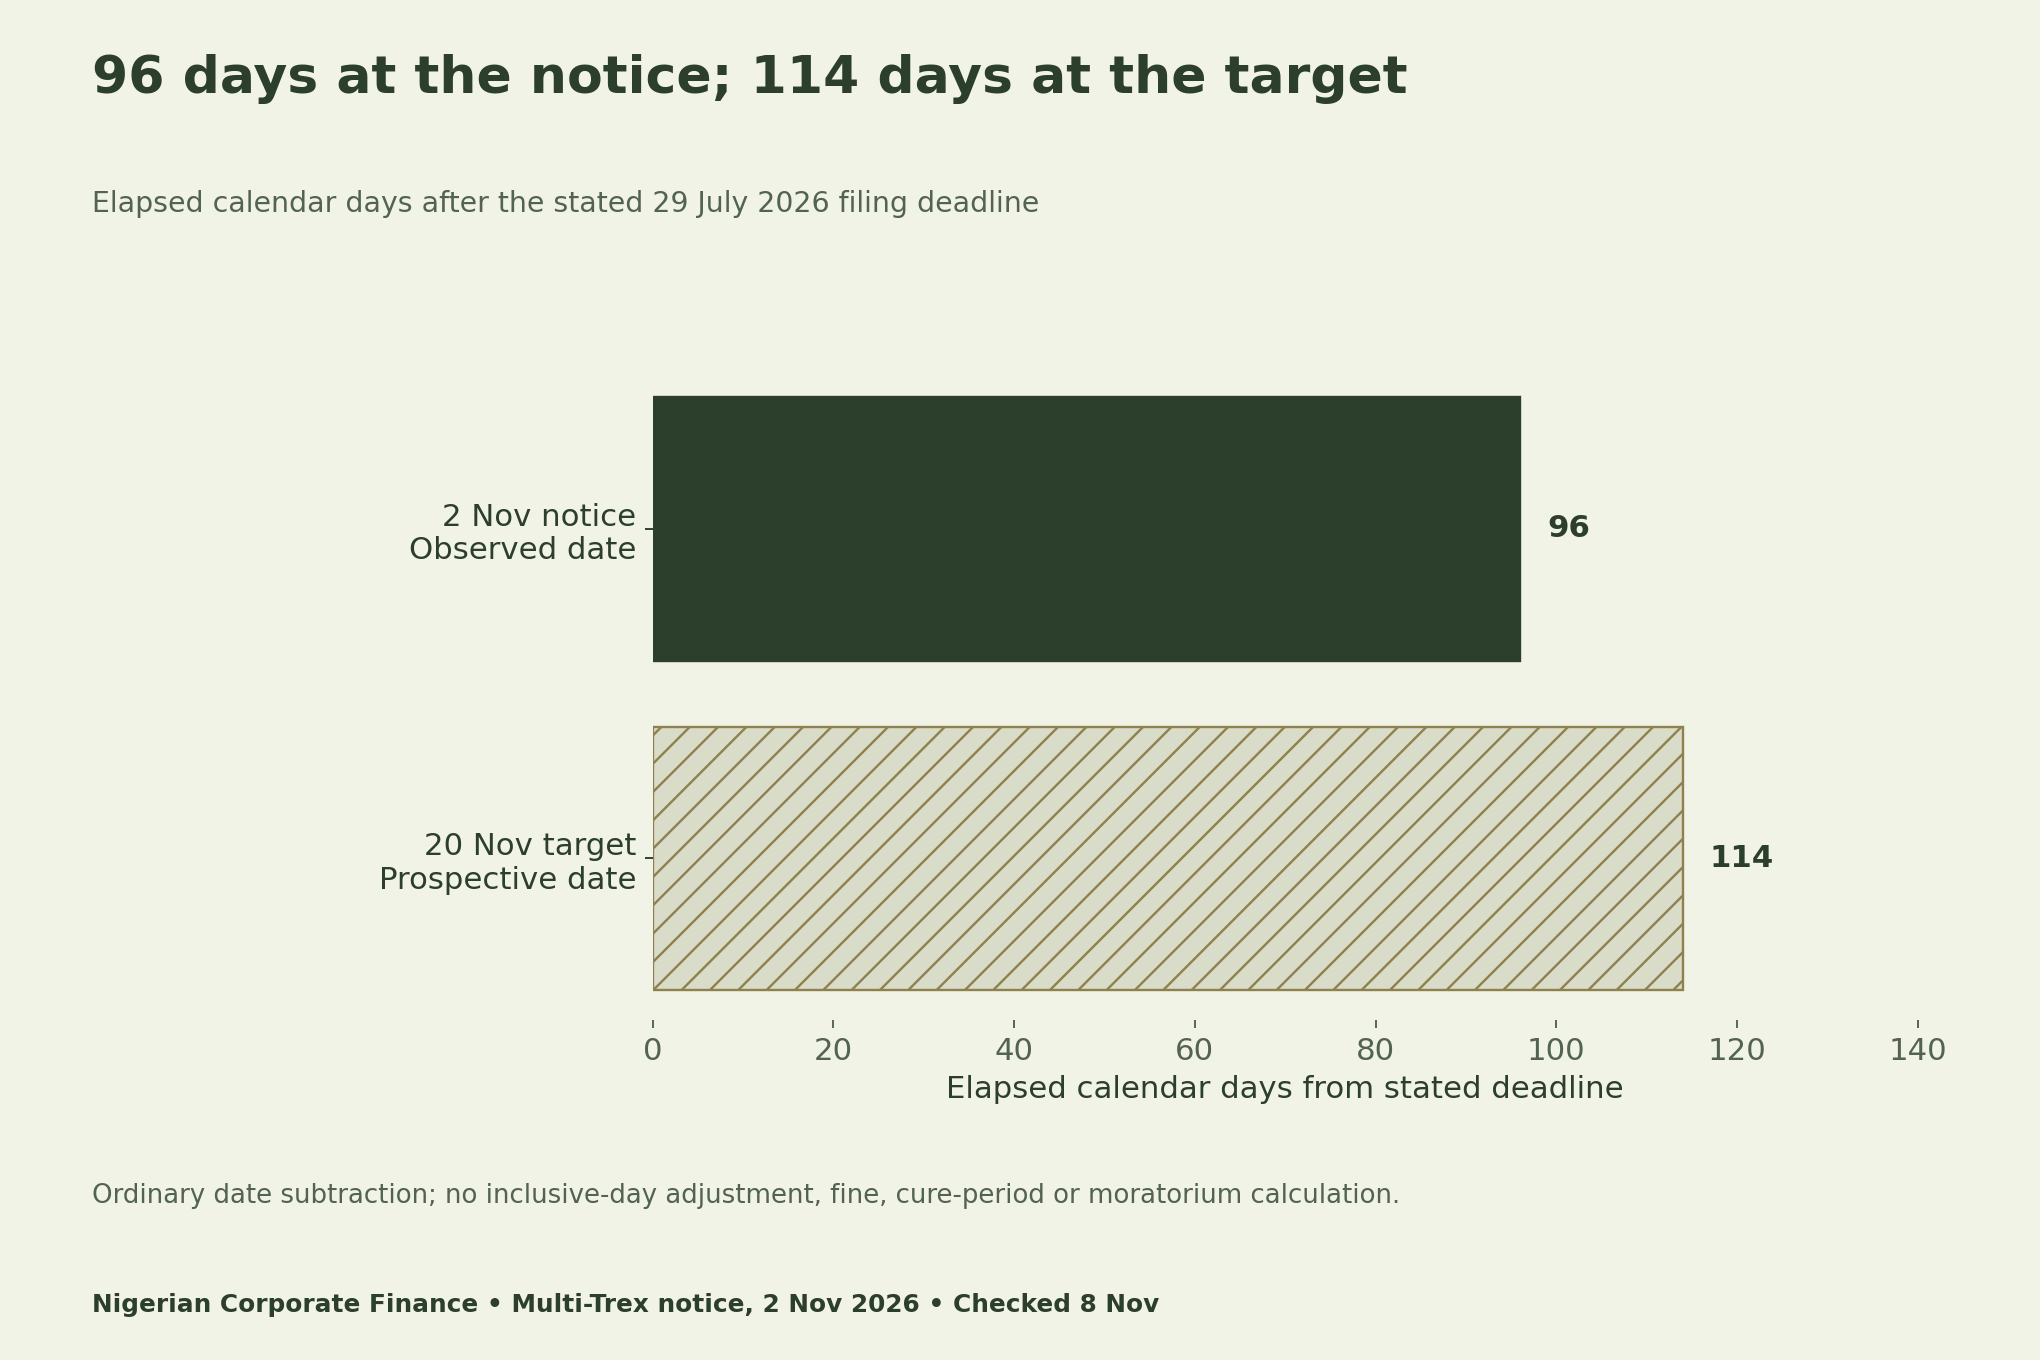
A precise interval is useful because readers can reproduce it. However, precision in date arithmetic does not validate an unverified legal conclusion. The numbers do not establish a penalty amount, an extension, immunity, fraud or the eventual audit opinion. Keep any such question out of a simple chronology unless separate evidence supports it.
Separate audit work, approval and public filing
Multi-Trex says its external auditors, Baker Tilly Nigeria, had concluded the audit. That is the company’s status statement in the delay notice. It is not the auditor’s report itself, and it does not reveal the wording of an eventual opinion. Avoid describing the audit as “clean” or “qualified” from this announcement alone.
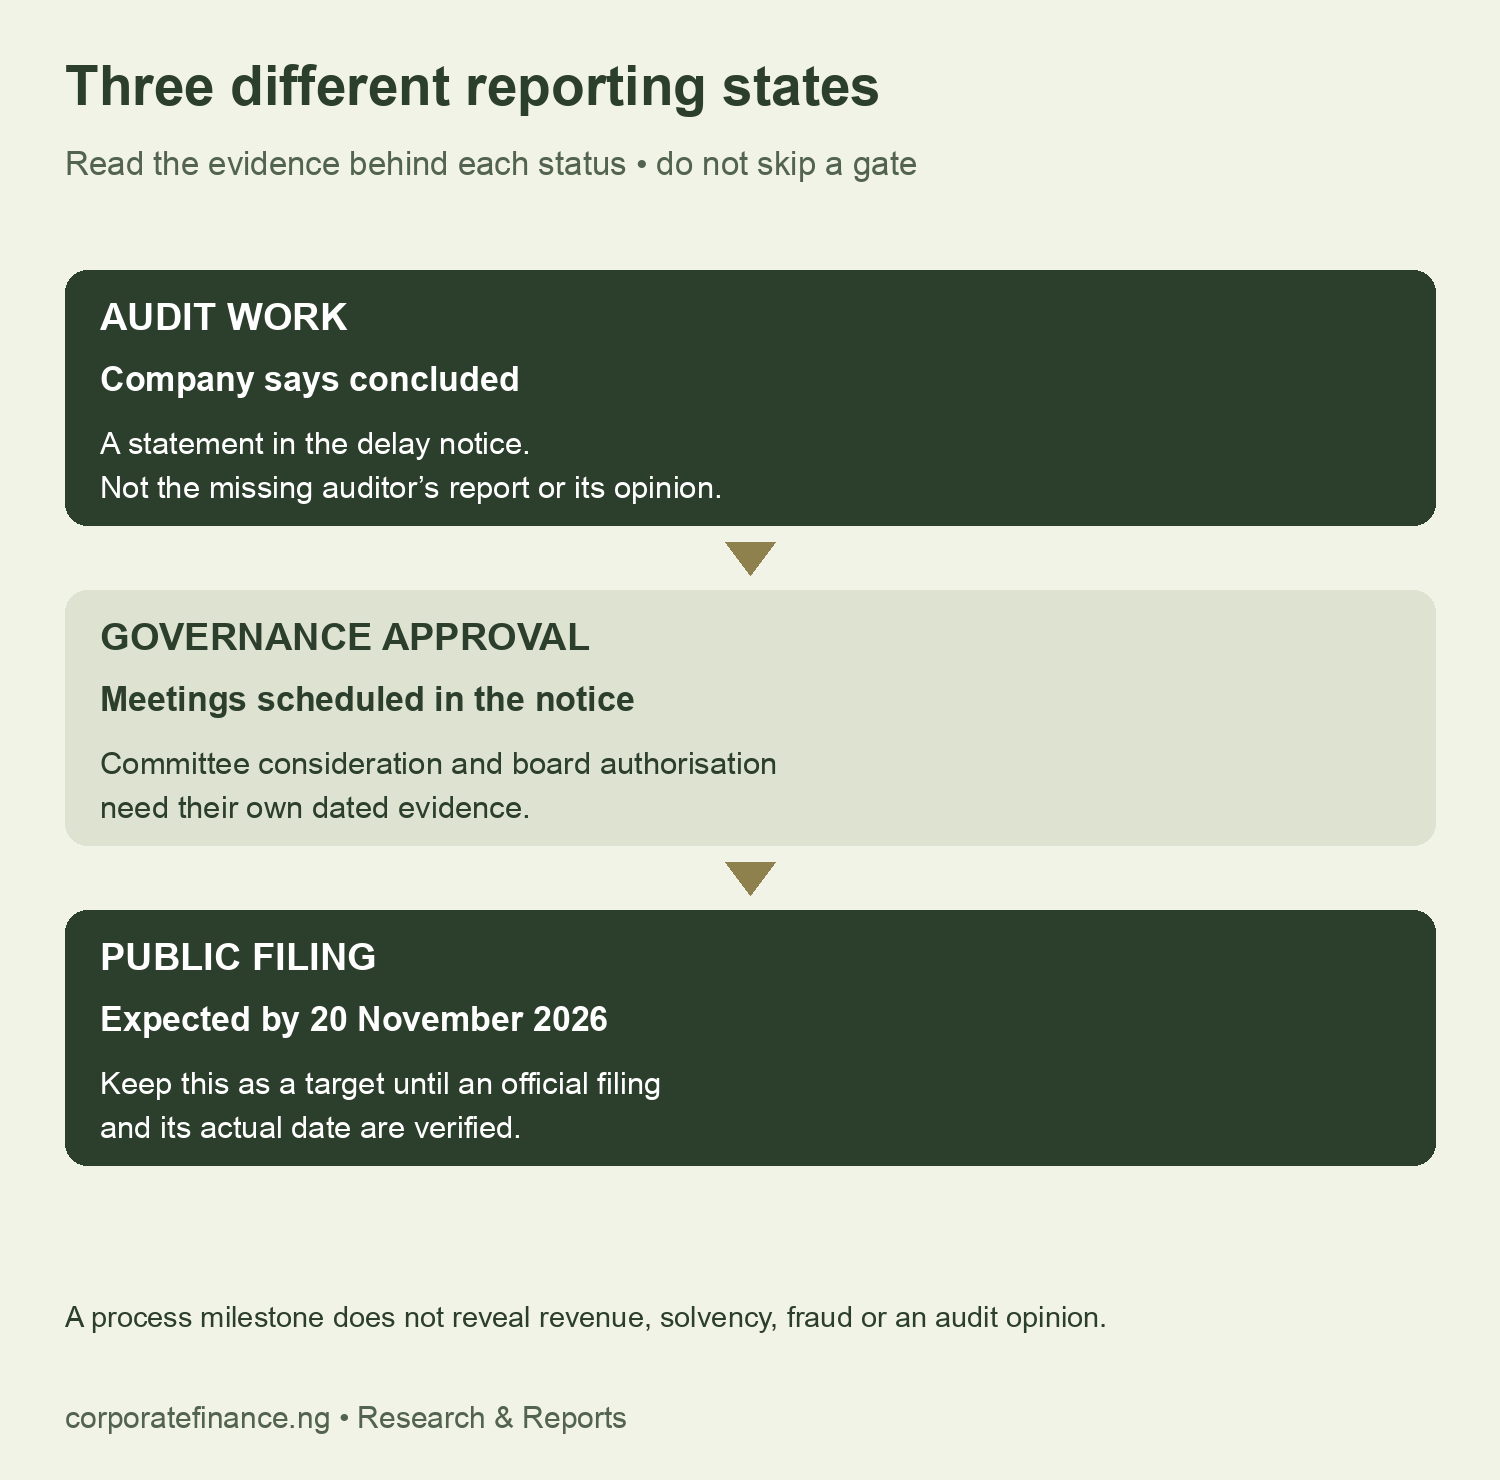
The notice lists scheduled meetings of the Statutory Audit Committee, Board Finance, Risk and Audit Committee, and full board to consider and approve the accounts. It says filing will follow approval. A process register should therefore retain the evidence supporting each stage, rather than replace all stages with a single “done” flag.
For an internal close process, assign an owner for the handoff and the document needed at each gate. A finance liaison, company-secretarial colleague and authorised filing officer may support different tasks. Those are illustrative roles in our template, not claims about Multi-Trex’s actual staff allocation or instructions to submit on the company’s behalf.
Attribute the explanation without adopting it as a finding
The company attributes the delay to reconstructing legacy accounting records following a seven-year AMCON intervention. It describes damaged or unavailable documentation and loss of institutional memory. It also refers to a two-year moratorium granted in November 2024. These are the issuer’s explanations, not independently established findings by this publication.
We have not reviewed the underlying intervention documents, moratorium terms or accounting-record reconstruction work. As a result, we do not infer what legal protection exists or whether a stated explanation resolves every reporting obligation. The educational lesson is narrower: a reporting-status note should identify its source and the evidence still needed.
Keep expected and actual filing dates in different fields
At this research check, the reviewed official NGX issuer page includes a 2026 unaudited Q4 statement and the delay notice. Those document labels matter. The unaudited filing is not a substitute for the completed audited accounts described as pending in the notice.
The version panel leaves actual filing date blank and preserves 20 November as expected. If a later editor locates the official audited filing, they should verify the reporting year, approval date, auditor report and version. Only then should they replace the status with a confirmed event and record the evidence. The panel is a reusable template, not a new monitoring commitment.
Our Briclinks source-quality guide shows why an approval field matters before interpreting accounts. The MTN appointment-date report also demonstrates the difference between an announcement and an event that becomes effective later.
Download the Multi-Trex delayed financial statements 2026 tools
The chronology file preserves event status and source fields. The interval file states the calendar formula. The close checklist assigns only illustrative roles, with actual owners left for an authorised team. The editorial version panel separates expected and actual filing. None of the files contains the missing audited accounts or predicts their financial results.
- Dated reporting chronology with prospective labels (CSV)
- Reproducible elapsed-calendar-day calculations (CSV)
- Blank reporting-close evidence and owner template (CSV)
- Expected-versus-actual filing version panel (CSV)
Methodology, limitations and citation
We transcribed dates and status statements from the two-page issuer notice and checked the official issuer-page links on 8 November. We calculated three intervals with ordinary date subtraction. Two figures describe chronology and elapsed time; additional statistical charts would imply financial or process-performance evidence the notice does not provide.
The notice is not the missing financial statements or an auditor’s report. It does not permit a conclusion about revenue, profit, solvency, fraud, an audit qualification or sanction amounts. The expected date may change. The issuer’s account of legacy challenges and the moratorium remains attributed rather than independently verified.
Suggested citation: Nigerian Corporate Finance (8 November 2026), “Multi-Trex Delayed Accounts: Track Audit, Approval and Filing”, using the issuer notice dated 2 November 2026. Preserve prospective status and the calendar-day convention when reusing the timeline.


